The Fixed Asset Register: What Belongs In It and Why Yours Is Wrong
What the register carries, why spreadsheets fail at scale, and the three reasons physical assets and the balance sheet drift apart.
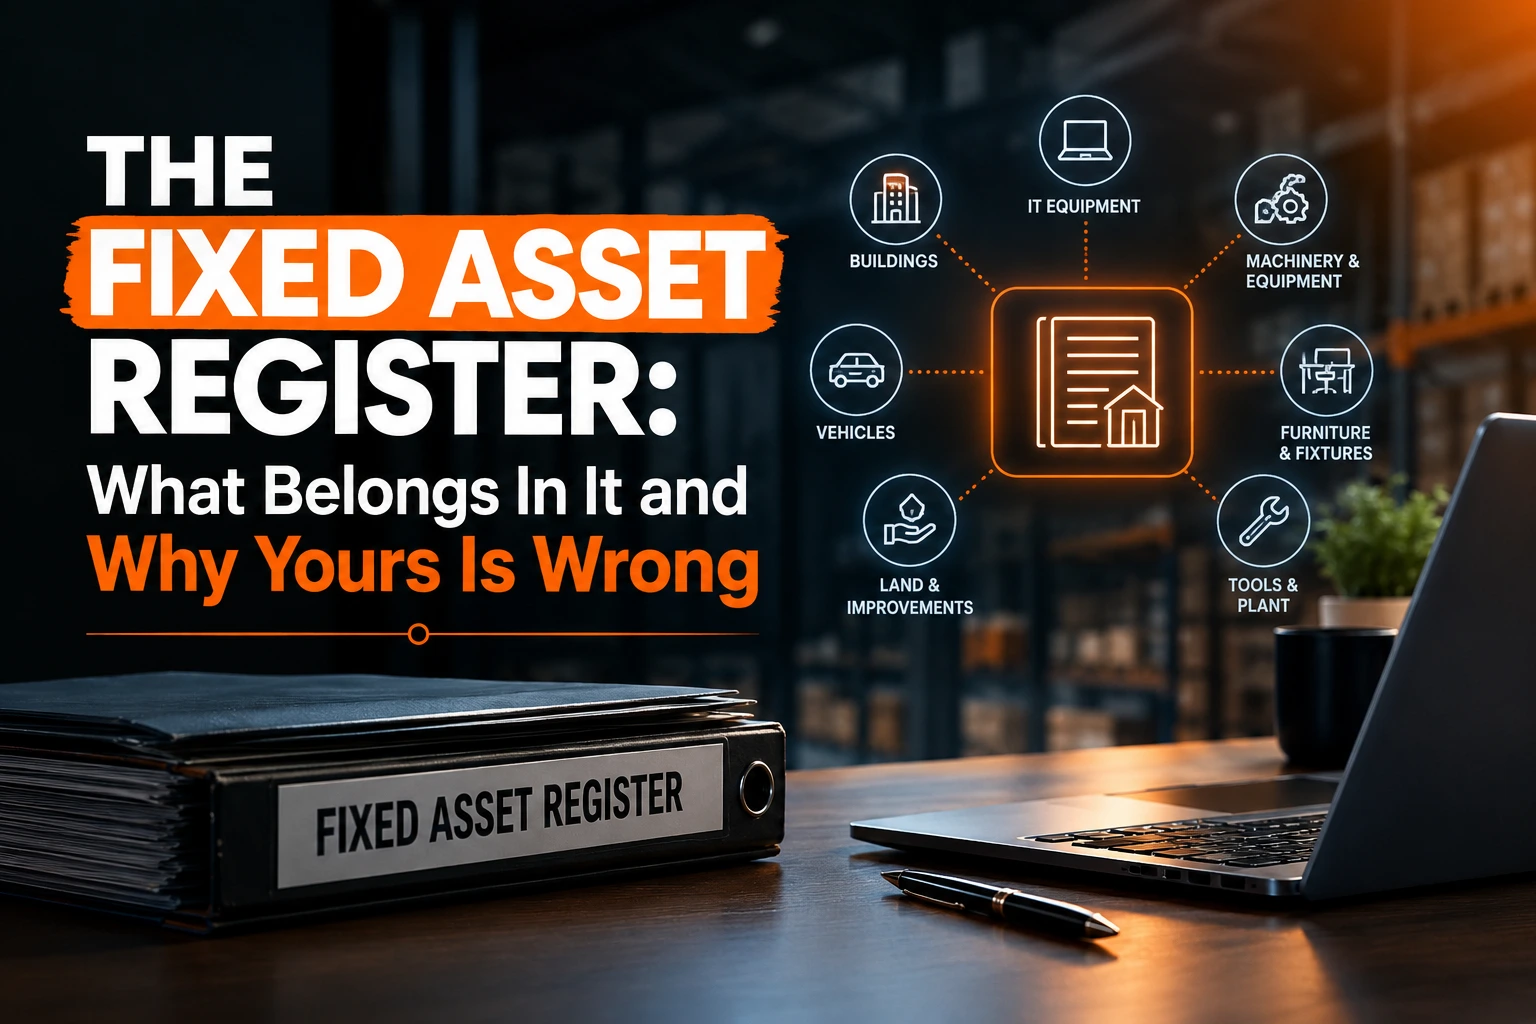
A fixed asset register is not an inventory of things you own. It is an accounting record that supports the balance sheet and the depreciation charge — and the physical equipment and the ledger drift apart the moment somebody discards, relocates, or expenses an asset without telling finance.
The short version
- A fixed asset register is an accounting record supporting the balance sheet, not an equipment list.
- An asset coded as an expense at purchase never enters the register in the first place.
- The three reasons registers fail are unrecorded disposals, untracked transfers, and misclassified purchases.
- Depreciation methods like straight-line and reducing-balance are accounting policy choices, not arbitrary settings.
- Physical verification fails if there is no defined authority on who can approve write-offs for missing items.
- Move to fixed asset register software when multiple sites, active disposals, or audit scrutiny make spreadsheets unmanageable.
What the register is actually for
The single most common mistake finance and operations teams make with fixed assets is treating the register as an IT inventory or facilities equipment list.
While an inventory asks "what do we have and where is it?", the asset register exists to answer a stricter accounting question: what capital investments did the organisation make, what is their book value today, how much economic benefit has been consumed as depreciation, and who is accountable for them?
Every line on the register ties directly to financial statements. When auditors review fixed assets, they are not merely checking whether an office chair exists in a conference room.
They are verifying whether the carrying value on the balance sheet reflects genuine ownership, whether the depreciation charge in the profit and loss statement follows an approved accounting policy, and whether impaired or discarded assets have been written off.
Because the register is an accounting record rather than a stock sheet, maintaining it by hand or in an isolated file creates immediate friction. Purpose-built fixed asset register software exists specifically to bridge this divide, establishing a verifiable trail between the physical reality on the plant floor and the financial ledger.
What a complete asset record has to carry
An incomplete record is the root cause of failed audits. To function as both an operational control and a statutory financial schedule, every record within modern fixed asset register software must track ten core attributes from acquisition to retirement.
1. Unique asset identifier. A permanent tag number or asset code assigned at commissioning. This identifier remains constant even if the asset changes departments, custodians, or physical buildings.
2. Standardised description and asset class. Generic labels like "Server" or "Laptop" guarantee confusion during physical audits. The record must document category, manufacturer, model, and serial number, mapped to an asset classification that defines its statutory accounting treatment.
3. Physical location. The specific site, plant, floor, or room where the asset is deployed. Without granular location tracking, annual verifications turn into weeks of fruitless searching across facilities.
4. Named custodian. Every asset requires an accountable individual or department head. When ownership is diffuse, equipment neglected or moved without authorisation goes completely unnoticed.
5. Acquisition date and capitalised cost. The date the asset was placed into service, alongside its total capitalised cost — including purchase price, freight, duties, and non-refundable taxes, matching the supplier invoice.
6. Capitalisation approval reference. The purchase requisition, purchase order, and invoice reference that authorised treating the spend as a long-term capital expenditure rather than an operating expense.
7. Useful economic life. The operational lifespan over which the business expects to extract value from the asset, defined by board policy and accounting standards.
8. Depreciation method and convention. The specific formula applied — such as straight-line or reducing-balance — along with salvage value conventions and monthly calculation rules.
9. Accumulated depreciation and net book value. The cumulative depreciation charged to date, and the resulting current carrying value on the general ledger.
10. Disposal and retirement details. The date of disposal, sale proceeds or scrap value, write-off authorization, and recorded gain or loss on derecognition.
Capitalise or expense: the decision where the problem starts
Long before an item ever reaches the register, its financial destiny is decided during the purchasing workflow. When a purchase requisition is approved, someone makes a classification choice: capitalise the expenditure as a fixed asset, or expense it immediately to the departmental cost centre.
This decision is governed by corporate policy rather than personal judgement. A robust capitalisation policy relies on three mandatory mechanisms: a formal monetary threshold, a minimum useful economic life requirement, and strict category consistency. If a purchase exceeds the threshold and will serve the business across multiple accounting periods, it must be capitalised.
This article publishes no specific rupee, dollar, or percentage thresholds. Capitalisation thresholds are established by your executive team in consultation with external auditors, and they vary widely based on organisation size, industry capital intensity, and tax regulations. What matters is that the threshold is unambiguous, documented in writing, and systematically enforced.
When businesses lack integration between their purchasing process and their asset register, operational staff inevitably classify durable assets as consumable office supplies or repairs. That expenditure is paid, expensed in the current month, and forgotten.
The equipment arrives on site, but it will never appear in the fixed asset register software, creating a "ghost asset" in reverse — physical equipment that exists in the building with zero record on the books.
Depreciation methods without the guesswork
Depreciation is not an estimate invented at year-end; it is the systematic allocation of an asset’s depreciable amount over its useful life. The method chosen directly dictates your annual profit figures and asset valuation.
The two primary depreciation conventions handled by fixed asset depreciation software are straight-line and reducing-balance.
Straight-line depreciation charges an equal expense across every full year of the asset’s estimated useful life. It is the standard approach for assets whose economic utility is consumed evenly over time, such as furniture, office fittings, and buildings. It is predictable, transparent, and straightforward to calculate.
Reducing-balance depreciation applies a constant percentage to the asset’s diminishing net book value each year. This creates higher depreciation charges in the early years of operation and lower charges in later years. It is standard for machinery, vehicles, and technology assets that experience rapid technological obsolescence or higher maintenance costs as they age.
Selecting a method is an accounting policy governance matter, not a technical configuration tweak. Under standard accounting frameworks like IFRS and local corporate statutes, once a depreciation method is chosen for an asset category, it must be applied consistently. Switching methods requires audit justification and formal notes in your annual financial statements.
Deploying dedicated asset depreciation software eliminates manual calculation errors, prorates mid-month acquisitions automatically, and posts monthly depreciation journals straight to the general ledger without spreadsheet formulas breaking under version updates.
The three reasons your register is wrong
Almost every finance director who conducts a fresh physical asset audit discovers that their existing register is materially incorrect. This drift rarely stems from incompetence; it is the inevitable outcome of three systemic workflow breakdowns.
1. Unrecorded disposals and scrap. An old desktop computer fails, a machine part is swapped out, or broken furniture is placed in a back room and eventually hauled away by building maintenance.
Nobody in operations fills out a disposal form, and nobody alerts finance. The item remains on the asset register for years, accumulating phantom depreciation and inflating the balance sheet, until an external audit or physical verification discovers it is gone.
2. Unrecorded transfers between sites and staff. An engineer takes a high-value diagnostic tool from the central plant to a regional branch for a three-day project and never returns it. A remote laptop is reassigned from a departing sales manager to a new hire without updating IT or finance.
The asset still exists and operates, but its location and cost-centre allocations in the register are completely wrong. When department managers receive their monthly depreciation charges, they dispute assets they no longer hold.
3. Assets expensed at purchasing. As highlighted in the capitalisation discussion, when requisitions bypass the finance review loop, capital items slip through as operational expense claims or general supplies. The company pays for the equipment, but no asset tag is generated, no record is created, and the balance sheet is understated.
The remedy for all three is not policing staff harder; it is connecting workflows. A modern fixed asset management solution links purchasing, custody changes, and disposal authorisations into an unbroken administrative trail.
The physical verification count and reconciliation
To keep the record defensible, organisations perform periodic physical asset verifications. But physical counting is only half the exercise — the real accounting challenge begins during reconciliation.
A physical count produces a list of what physically exists in each room and plant today. While operational teams rely on scanning tools and mobile verification apps for physical capture, the finance team must take that raw count and reconcile it against the historical asset register.
Reconciliation inevitably produces discrepancies, categorised into two groups:
Unmatched physical items. Equipment found on site that carries no tag, an unreadable tag, or does not match any open record on the register. These require investigation: was this item expensed at purchase, leased from a third party, or moved from another branch without paperwork?
Missing register items. Assets that appear active with positive net book value on the register but cannot be found anywhere in the designated facility. If a thorough search confirms the item is lost, stolen, or scrapped, it must be derecognised.
Here lies the crucial governance control: who is authorised to write off the variance? An operations supervisor cannot unilaterally declare an expensive missing machine "written off".
Fixed asset inventory software enforces separation of duties, ensuring that missing items are flagged, investigated, and submitted to executive leadership and the board for formal write-off approval before the impairment journal hits the ledger.
Custody: why location alone is not enough
Recording that a company laptop is located in "Head Office, Floor 3" sounds sufficient until that laptop goes missing. "Floor 3" is not a person; it cannot be held responsible for taking care of equipment or handing it back during employee separation.
True operational control requires pairing a physical location with an individual custodian. Every asset must be formally assigned to a named staff member or department head who signs an acknowledgement upon receipt.
When that employee resigns or transfers, fixed asset tracking software cross-references their custody record during the exit clearance process, preventing company property from walking out the door unrecorded.
Furthermore, custody tracking establishes accountability for routine maintenance and safety compliance. For plant machinery, industrial boilers, and corporate fleets, the designated custodian is the individual responsible for scheduling statutory inspections and logging service history.
When a spreadsheet stops being defensible
For a young company with fifty desks, a single office, and ten computers, a spreadsheet is entirely defensible. It costs nothing, everyone knows where everything is, and year-end depreciation takes an afternoon to calculate.
A spreadsheet stops working at three precise operational milestones, and they almost always arrive simultaneously:
Multiple locations and remote teams. As soon as equipment is spread across branches, warehouses, or remote home offices, a static workbook cannot keep pace with daily transfers. Multiple managers edit local copies, resulting in conflicting versions that nobody can reconcile.
Active disposal and replacement volume. When an organisation begins retiring, upgrading, and selling dozens of assets monthly, tracking partial disposals, accumulated depreciation reversals, and salvage proceeds in formulas becomes an audit liability.
Statutory and auditor scrutiny. The moment external auditors ask for an immutable audit trail — who changed an asset’s useful life, who authorised a revaluation, and who approved a write-off — a spreadsheet fails. Anyone can change a cell in Excel without leaving a trace.
At that threshold, investing in fixed asset register software is not about buying fancy features. It is about acquiring three vital controls: automated depreciation calculation that matches your statutory rules, an unalterable audit log of every asset movement, and seamless integration with your financial ledger.
A dedicated fixed asset system unites purchasing, physical custody, and accounting schedules on a single reliable ledger.
When asset records operate inside a unified fixed asset management system connected directly to procurement software, goods receipt, asset creation, and financial depreciation form a single, continuous workflow. That is the fundamental strength of managing capital assets within a comprehensive erp system: you eliminate the friction between what operations uses and what finance reports.
To ensure that the initial procurement step captures capital items properly before they ever enter the register, review our practical guide to the purchase order process. And if you are managing both short-term raw materials and long-term capital spares, see how they differ in our breakdown of perpetual versus periodic inventory methods.
By treating the fixed asset register as the vital accounting control it truly is, and supporting it with modern fixed asset management tools, finance leaders can finally retire the spreadsheet guesswork and face their annual audits with complete confidence.
An asset enters at purchase, depreciates on the balance sheet, and leaves on disposal. Tracking that lifecycle without reconciling spreadsheets against bank statements is what an erp system is built to do.